Starbucks Plans $1B Store Overhaul — Can Margins Hold Up?
Starbucks is betting $1 billion on cozier stores, but investors want to know if the vibe upgrade pays off.
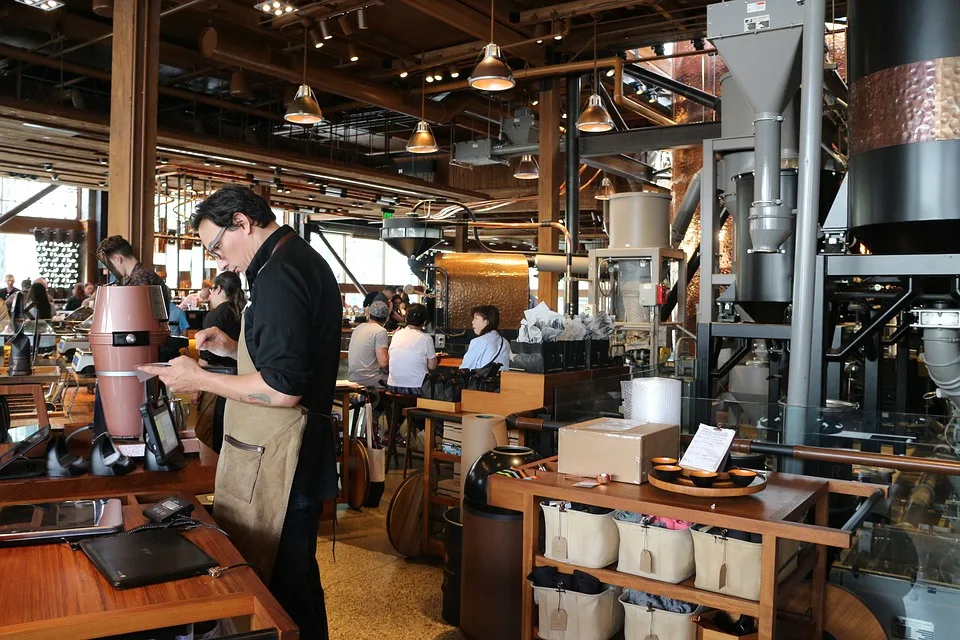
Starbucks is going all-in on atmosphere. The coffee giant is committing $1 billion to redesign its store footprint, chasing a more inviting, sit-down experience it hopes will win back customers who've drifted toward cheaper or trendier competitors. It's a bold swing — and Wall Street is watching every penny.
The core thesis is simple: if stores feel better, customers stay longer and spend more. CEO Brian Niccol has made the physical store experience a centerpiece of his turnaround playbook, betting that ambiance can move the needle on both traffic and ticket size. That's the kind of brand-first thinking that worked at Chipotle. Now he's trying to transplant it to a global coffee empire.
Read more J&J's Ottava Robot Takes Aim at Lucrative Surgery Market →
Here's the tension traders should watch. Capital-heavy remodels compress near-term margins. A billion dollars spread across thousands of locations is not a rounding error — it shows up in depreciation, labor disruption, and temporary sales drag during construction windows. If comparable-store sales don't respond quickly, the margin story gets ugly fast.
Starbucks already faces pressure on multiple fronts: sluggish traffic in the US, a brutal sales environment in China, and consumers who are increasingly price-sensitive. Betting on cozy when your customer is skipping the $7 latte entirely is a genuine strategic risk. The redesign has to drive enough incremental volume to justify the spend — or the Street will punish the stock for prioritizing vibes over returns.
This is a show-me moment for Niccol. The turnaround narrative is intact for now, but patient money won't wait forever for proof that prettier stores actually translate to fatter margins. Continue reading at Yahoo Finance.


